"It's just a temporary thing. We'll top it back up on Friday."
That's what the office manager at a small conveyancing firm in Ipoh told the managing partner, after quietly moving RM3,200 from the client account to cover a printer lease payment that was overdue. The firm's office account was running low that week — a slow month, a few clients paying late — and the client account had a healthy balance sitting in it from a completed transaction, waiting to be disbursed.
Friday came. So did a new expense. The RM3,200 never made it back that week. Or the next.
Nobody set out to do anything wrong. It felt, at the time, like moving money between two pockets of the same coat. But a client account and an office account are not the same pocket. And once the line between them blurs — even briefly, even with good intentions — it tends to blur again.
Why This Matters More Than It Seems
Malaysian legal practice rules, a law firm's client account and office account must be kept structurally separate. The client account holds money that belongs to clients — retainers, deposits, sale proceeds, funds held pending completion of a transaction. The office account holds the firm's own money, including fees the firm has actually earned and billed.
This isn't a bookkeeping preference. It's a professional obligation. Client money is held on trust, and using it — even temporarily, even with the intention to "pay it back" — for the firm's own expenses is exactly the kind of thing that draws serious scrutiny from the Bar Council if it comes to light.
The uncomfortable truth is that most firms don't discover a client-office account mix-up while it's happening. They discover it during a reconciliation, an audit, or when a client asks a pointed question about their money and nobody can give a clean answer.
The Pattern I Keep Seeing
Talk to enough Malaysian law firms about how they actually run their accounts day to day, and the same habits keep showing up:
- "Borrowing" from the client account to cover a short-term office cash flow gap, with every intention of putting it back — until the next gap arrives before the last one is fixed
- Disbursements paid from whichever account has the balance, rather than the account they're supposed to come from, because it's convenient in the moment
- One shared bank account doing double duty, with client and office money distinguished only by notes in a spreadsheet, not by any actual structural separation
- Fee earners unsure which account a transaction belongs to — especially newer associates or clerks who've never been walked through the distinction properly
- SST and billing treated the same way regardless of account — even though SST applies to the firm's fees in the office account, not to client funds simply passing through
- Manual transfers between accounts done by whoever's free that day, with no consistent approval step or record of why the transfer happened
- Reconciliation postponed because it means manually checking two sets of records against a bank statement, and nobody has a spare afternoon for that most weeks
None of this usually starts as fraud. It starts as convenience — a shortcut taken under pressure, in a firm that never quite got around to building a system that makes the shortcut unnecessary.
What This Actually Costs a Firm
A blurred line between client and office accounts rarely announces itself immediately. It tends to surface later, and by then the cost has grown:
- Disciplinary exposure. Using client money for office purposes, even briefly and even if fully repaid, is treated seriously under the rules governing legal practice — intent matters less than most fee earners assume.
- A scramble at audit time. If the firm's accountant or a Bar Council auditor can't clearly trace which money belongs to whom, what should be a routine check turns into days of reconstruction.
- Cash flow that looks healthier than it is. A firm that's been quietly dipping into the client account to smooth over office shortfalls has no real picture of its own financial position — the office account looks fine because it's being propped up by money that isn't the firm's.
- Client trust, once questioned, is hard to fully repair. A client who senses their funds weren't handled cleanly rarely lets it go, even after the money is accounted for.
- Partner time burned on firefighting. Every hour spent untangling which account a transaction should have come from is an hour not spent on billable work.
Common Misconceptions
Misconception 1: "It's fine as long as we pay it back before anyone checks."
Reality: The obligation is to keep the accounts separate at all times, not to restore the balance before the next audit. A shortfall that existed for even a few days is still a shortfall, regardless of whether it was corrected later.
Misconception 2: "We're a small firm — this level of separation is overkill for us."
Reality: The rules on client money apply regardless of firm size. Smaller firms often run a leaner team, which can mean fewer people double-checking transfers, not fewer risks.
Misconception 3: "As long as it's tracked in a spreadsheet, we're technically separate."
Reality: Labelling columns "client" and "office" in the same spreadsheet, drawn from the same bank account, isn't structural separation. It's a label, not a barrier — and it's exactly the kind of thing that falls apart under a genuine audit.
Misconception 4: "SST doesn't really factor into this — that's an accounting team problem."
Reality: SST applies to the fees a firm earns, which sit in the office account. If office and client money aren't cleanly separated, working out what's actually subject to SST becomes a guessing exercise rather than a calculation.
Misconception 5: "Our bank statement is proof enough of where the money is."
Reality: A bank statement shows where money sits, not who it belongs to. Without a system that ties every transaction back to a specific matter and account type, the bank statement alone tells you very little.
What Proper Separation Actually Looks Like
Before getting into how software helps here, it's worth being specific about what "properly separated" actually means in practice — because a lot of firms have never seen it in action.
- Client and office accounts exist as genuinely distinct ledgers, not just distinct labels within one shared record. Money can't accidentally cross from one to the other without a deliberate, recorded transfer.
- Every transfer between accounts requires a clear reason and leaves a record — which matter it relates to, why it was made, and who authorised it. Nothing moves quietly.
- Disbursements are tagged to the correct account automatically at the point they happen, not decided case-by-case based on which account has a balance that week.
- Reconciliation happens regularly enough that a discrepancy is caught within days, not months — ideally as part of routine operations, not a special annual project.
- Every fee earner, regardless of seniority, works within a system that makes the correct account obvious, rather than relying on individual judgment or memory.
- SST calculations apply cleanly to office account transactions, because the office account only ever contains the firm's own earned fees — not client money that happens to be sitting nearby.
- A clean, exportable record exists for every transaction, ready to hand to an accountant, a partner, or a Bar Council auditor without needing to reconstruct anything from memory.
That's the standard. Reaching it with a shared bank account and a well-meant spreadsheet is difficult even for a disciplined firm — not because the people involved are careless, but because the tools weren't built to enforce the separation in the first place.
Where a System Like EasyPro Fits In
This is usually the point where firms realise the issue was never really about discipline. It was about not having a system built to keep client and office money apart by design.
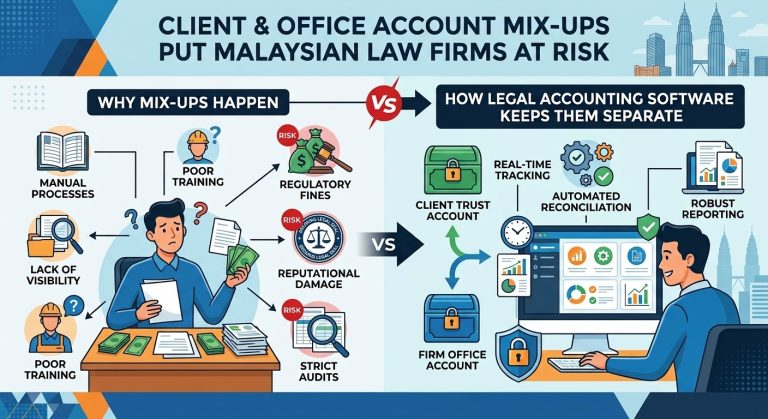
EasyPro's accounting management module structurally separates the client account and office account at the system level — they aren't two labelled columns in the same spreadsheet, but two genuinely distinct ledgers. When a fee earner records a disbursement or a receipt, it's tagged to the correct account and the correct matter automatically, so nothing depends on someone remembering which pocket the money is supposed to sit in.
Transfers between the client account and office account go through a clear, recorded process rather than an informal bank transfer done under pressure — every movement of funds is traceable back to a specific matter and a specific reason. Bank reconciliation runs against both ledgers, so a mismatch surfaces close to when it happens rather than months later. And because the office account only ever holds the firm's own earned fees, SST calculations and reporting work off clean numbers rather than a mix of client and office money that has to be untangled first.
It's built around how Malaysian firms actually operate — multiple fee earners handling client funds on shared matters, disbursements paid out on a client's behalf, retainers held against future costs, and a Bar Council and LHDN framework that both expect the two account types to stay genuinely apart. The goal isn't to replace the partners' oversight of the firm's finances. It's to make sure that oversight is working with accurate numbers, rather than against a system that lets the lines blur when nobody's looking closely.
Client & Office Account FAQ
What's the actual difference between a client account and an office account?
The client account holds money belonging to clients — deposits, retainers, and funds held on their behalf pending completion of a matter — while the office account holds the firm's own money, including fees that have actually been earned and billed. Malaysian legal practice rules require these to be kept clearly and structurally separate.
Is it ever acceptable to use client account money to cover an office expense temporarily?
No. Even a short-term "borrow it back on payday" transfer uses client money for a purpose it wasn't held for, and this is treated seriously under professional conduct rules regardless of intent or how quickly it's repaid.
How does SST relate to client and office accounts?
SST applies to the fees a law firm earns for its services, which belong in the office account. Client funds simply passing through the firm — such as disbursements or held deposits — aren't the firm's income and shouldn't be conflated with SST-relevant transactions.
Can a small firm run both accounts through the same bank account with careful labelling?
It's possible in theory, but labelling within a single account isn't the same as structural separation, and it's difficult to maintain accurately over time, especially with more than one person handling transactions. Most firms find they outgrow this approach faster than expected.
How often should client and office accounts be reconciled?
As frequently as is realistically manageable — ideally as an ongoing part of operations rather than a periodic catch-up. The longer a discrepancy goes unnoticed, the harder it becomes to trace back to its source.
What happens if a Bar Council audit finds unclear separation between the two accounts?
The outcome depends on the specifics, but unclear separation between client and office funds is one of the areas auditors focus on closely, and it can lead to further inquiry even where no funds are actually missing. Firms should check current requirements directly with the Bar Council rather than relying on informal assumptions.
Does accounting software replace the need for a firm's own accountant?
No. It gives the accountant and the partners accurate, structurally separated numbers to work from, rather than a reconstruction job built from a shared bank account and manual notes. It reduces the manual untangling, not the oversight.
How long does it typically take to move from a shared account setup to proper separation?
This depends on the firm's size and how mixed the existing records are, but most firms see a clear improvement within the first billing cycle or two once matters, client funds, and office funds are properly structured in a system built for it.
Worth a Look
If any part of this sounded familiar — a transfer that was meant to be "just this once," an account balance that doesn't quite add up, a reconciliation you've been putting off — it might be worth seeing how EasyPro's accounting module keeps client and office money genuinely apart. A short demo usually makes the difference between "labelled and hoping" and "structurally separated" pretty clear.